A firm offer on the home you are buying is exciting. It can also create a cash-flow problem when your current property has not sold, has not closed, or will close after your purchase. Bridge loan financing is designed for that narrow gap, giving qualified homeowners temporary access to the equity tied up in their existing home.
For Toronto and GTA move-up buyers, timing can matter as much as price. The right purchase may appear before your sale is complete. A bridge loan can make the dates work, but it is not automatic, inexpensive, or suitable for every situation. The smart approach is to understand the lender’s conditions before you make an offer that depends on short-term financing.
What is bridge loan financing?
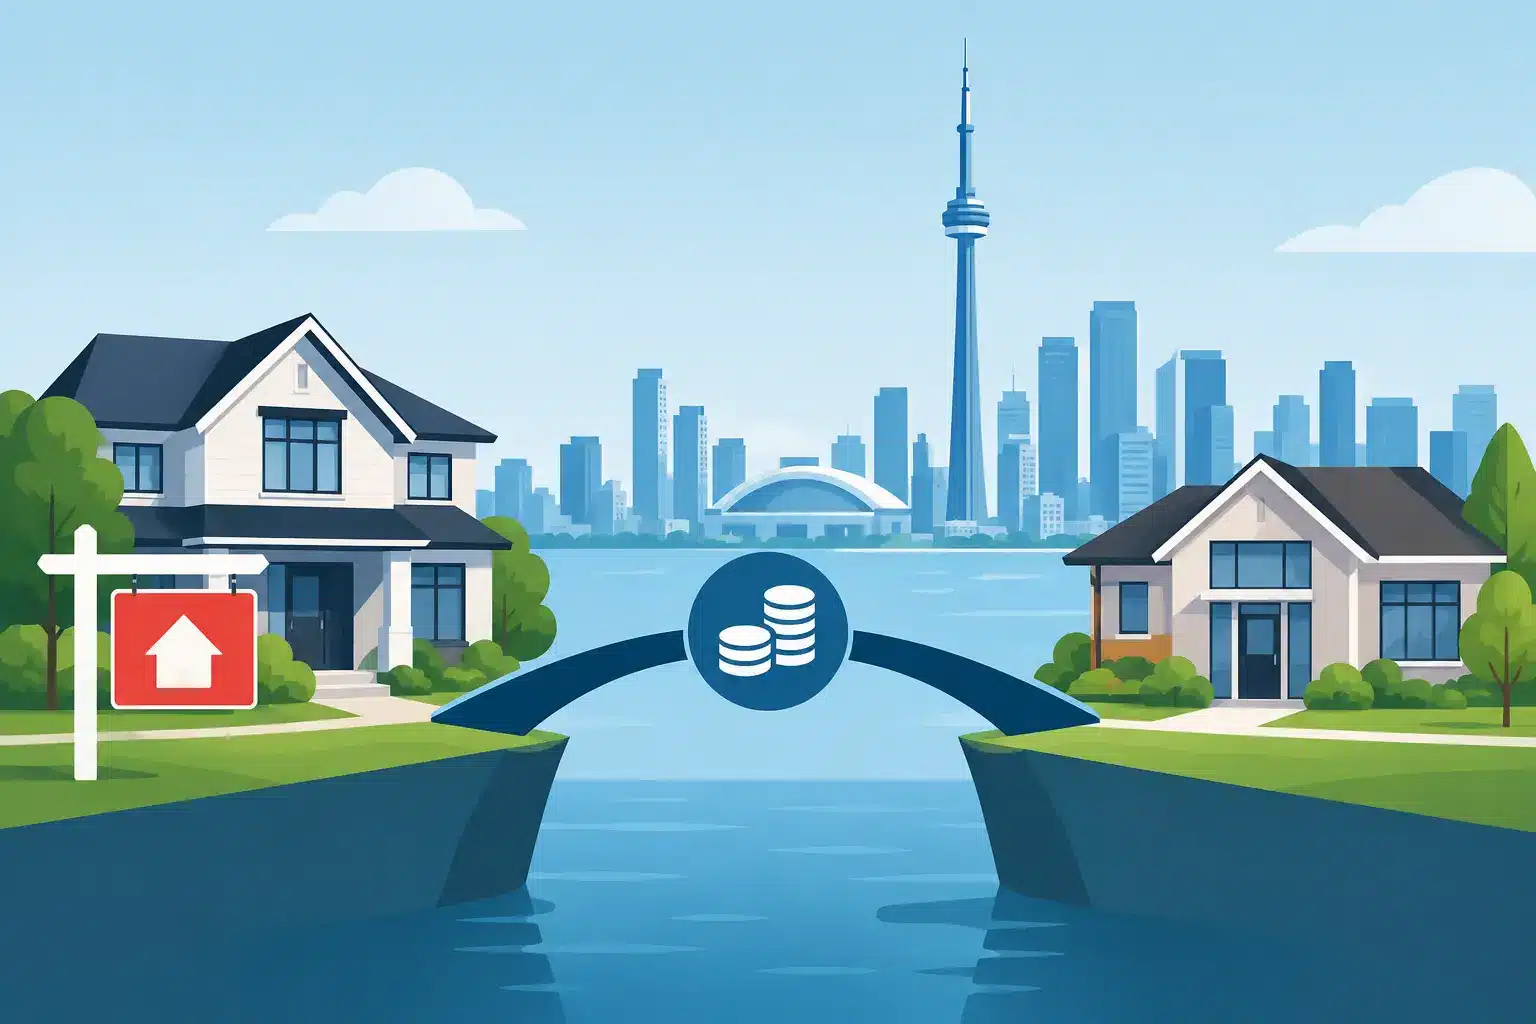
A bridge loan is short-term financing secured against real estate. It covers the period between buying a new home and receiving the proceeds from the sale of your current one. In a typical scenario, you use the funds for the down payment, closing costs, or a portion of the purchase price on the new property. Once your existing home closes, the sale proceeds repay the bridge loan.
Most Canadian lenders treat bridge financing as a temporary solution, often for a few weeks or months rather than a long-term borrowing strategy. The expected repayment source is central to the approval decision. A lender wants confidence that your current home will sell and that the net proceeds will be enough to clear the bridge loan, existing mortgage, and related costs.
That is why a lender will usually review both transactions closely. They may require a firm agreement of purchase and sale for your current home, a firm purchase agreement for the new property, mortgage details, property values, and evidence of your income and overall debt obligations.
When a bridge loan can make sense
Bridge financing is most useful when the fundamentals are strong but the closing dates do not line up. Perhaps you have accepted a solid offer on your Toronto condo with a 60-day closing, but the detached home your family wants closes in 30 days. The equity is there. You simply need access to it before your buyer’s funds arrive.
It can also help a seller make a competitive offer on a replacement property without inserting a sale-of-property condition. In a competitive GTA market, a cleaner offer can be more attractive to a seller. That said, removing conditions increases your exposure. It should only be done after confirming what financing is available and what happens if your own sale is delayed.
Bridge loan financing may be a reasonable fit when your current home is already sold firm, the closing gap is short, and you have enough equity to support both transactions. It can be less appropriate when your home is merely listed, the asking price is optimistic, or the repayment plan depends on a quick sale at a number the market may not support.
The difference between a sold home and a listed home
This distinction matters more than many homeowners expect.
With a firm sale in place, the lender can assess an actual sale price, closing date, deposit, and purchaser. Approval is generally more straightforward because the exit plan is clear. The lender will still account for mortgage payouts, real estate fees, legal fees, adjustments, and any other obligations that reduce your net proceeds.
With only a listing, bridge financing can be more difficult to arrange. Some lenders will consider it, particularly where there is substantial equity and strong borrower income, but the terms may be stricter and the cost higher. Private financing may be the only option in some cases, which requires especially careful review. Higher rates and lender fees can quickly turn a timing solution into an expensive problem.
A strong sale strategy helps reduce this uncertainty. Accurate pricing, professional presentation, broad exposure, and disciplined negotiation are not just marketing details when your next purchase depends on your sale closing. They affect your timeline, confidence, and borrowing options.
Costs to budget for before you commit
Bridge loans are not priced like a standard long-term mortgage. Interest rates, lender fees, legal costs, appraisal requirements, and administration charges vary by lender and by the strength of the file. Some lenders charge interest only for the period used, while others may have minimum fees or specific repayment provisions.
The cost is often manageable when the bridge period is short. But a short period can become longer if a closing is delayed, a buyer requests an extension, or a deal falls apart before becoming firm. Homeowners should budget for more than the ideal scenario.
Do not focus only on the bridge loan rate. Ask for the full cost of borrowing, including lender, legal, discharge, and appraisal fees. Confirm whether the interest is paid monthly or deducted from the advance. Also ask what happens if your sale closes late, whether an extension is available, and what the extension would cost.
Your carrying costs matter too. For a period of time, you may be responsible for mortgage payments, property taxes, insurance, utilities, and maintenance on two homes. A lender may qualify you based on those obligations, but your own budget should be more conservative than the minimum approval calculation.
How lenders assess a bridge financing request
Lenders generally look at the value and saleability of both properties, the equity in your current home, the outstanding mortgage balance, your income, credit profile, and the details of each purchase and sale agreement. They will calculate whether the expected sale proceeds provide a credible repayment path.
A clean file makes a real difference. Have current mortgage statements available, along with purchase and sale documents, deposit information, property tax details, and identification. If you are self-employed or have variable income, prepare the same income documentation you would expect for a regular mortgage application.
The lender will also look at timing. A 15-day gap between closings is a different risk than a 120-day gap. Neither is automatically impossible, but a longer period means more interest, more market exposure, and a greater chance that something changes before repayment.
Questions worth asking your lender or mortgage professional
Before waiving any financing or sale-related condition, get clear answers. What is the maximum bridge amount? Is approval based on a firm sale or can it be approved with a listing? What assumptions are being used for the expected net proceeds? What are the total fees? And what is the backup plan if the sale does not close as scheduled?
A verbal indication is not the same as a confirmed financing commitment. Make sure you understand the conditions that remain outstanding and who must satisfy them.
Risks that deserve a direct conversation
The biggest risk is treating bridge financing as a substitute for a sale plan. If your current property has not sold, you may face pressure to reduce the price, accept weaker terms, or obtain more costly financing. That pressure can erode the equity you were trying to protect.
There is also deal risk. A buyer’s financing, inspection, or status certificate condition can fail before the sale becomes firm. Even after conditions are removed, unforeseen closing issues can arise. No transaction is risk-free, which is why a contingency reserve and realistic timeline are valuable.
For some homeowners, selling first is the financially safer choice. It provides certainty about net proceeds and lets you shop with a defined budget. The trade-off is that you may need temporary accommodation or may not find the right replacement home immediately. For others, buying first is appropriate because the desired home is difficult to replace and their equity, income, and financing position are strong. The right decision depends on your risk tolerance, market segment, and household cash flow.
Plan the sale and purchase together
A bridge loan should be part of a coordinated move, not a last-minute patch. Before listing, establish a realistic value range for your home, estimate your net sale proceeds, review mortgage payout penalties, and discuss the likely timing of your purchase. If you are buying first, speak with a mortgage professional early enough to understand your limits before you negotiate.
Your real estate strategy should support the financing strategy. A listing price that attracts qualified buyers, thoughtful preparation, and a clear plan for reviewing offers can reduce the time your capital is tied up. At One Percentage Guys, that planning also includes a sharp focus on protecting the equity you have built, because every avoidable cost affects what you carry into your next home.
If bridge financing is on the table, aim for clarity rather than optimism. Know your expected net proceeds, confirm your lender’s conditions in writing, leave room for delays, and make purchase decisions that your household can carry comfortably. A well-timed move can preserve both your buying opportunity and your financial flexibility.